
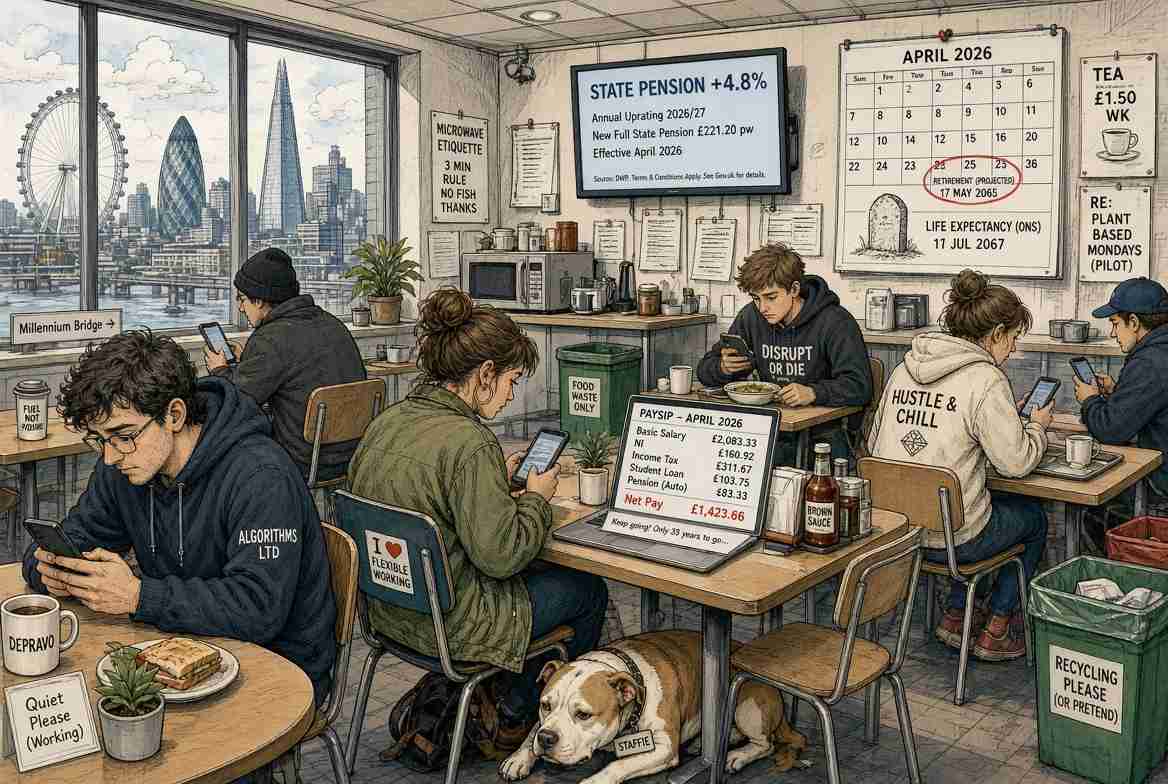
Government Reassures Generation Rent That Retirement Remains Available in Theory
LONDON – Britain’s younger workers received encouraging news this year after the State Pension increased by 4.8%, allowing millions to begin planning confidently for the glorious retirement they may eventually enjoy somewhere between their final performance review and embalming.
What the 4.8% State Pension Rise Means If You’re Under 40
The full new State Pension rose to £241.30 a week from April 2026 under the triple lock.
Young Britons welcomed the announcement by opening pension calculators, staring at the screen for several minutes, and returning to work.
“I’m delighted,” said a satirical 29-year-old renter paying £1,800 monthly for a cupboard with broadband. “Apparently if I continue contributing for another four decades, maintain uninterrupted employment, save independently, avoid illness, inherit property and develop the lifespan of a Greenland shark, things are looking excellent.”
Morag Sinclair, a Glaswegian who still cannot believe London rents, was appalled: “A cupboard wi’ broadband for £1,800? In Glasgow that’s a castle wi’ a moat and a man called Angus to fill it. In London it’s ‘compact and full of character’, which is estate-agent for ‘you’ll be sleeping in the wardrobe’.”
The British Retirement Social Contract, or How to Pay Twice
Government guidance still makes clear that eligibility and the amount received depend on an individual’s National Insurance record.
This has produced an unusual British social contract.
Workers pay taxes today to support current public expenditure.
They make workplace pension contributions for tomorrow.
They save privately in case tomorrow develops administrative difficulties.
Then they buy lottery tickets in case economics develops administrative difficulties.
Younger adults have therefore begun preparing for retirement using what financial advisers call the Four-Pillar System:
State Pension.
Workplace pension.
Private savings.
Having wealthy parents.
The fourth pillar has shown remarkable returns.
Alan Nafzger, who edits this newspaper and has sat across from more than one financial adviser, says the Four-Pillar System is architecturally sound provided you don’t look at the fourth pillar too closely. It is load-bearing, he points out, but it is holding up an inheritance nobody has written yet, currently sitting in the will of a man called Derek who has just taken up marathon running.
State Pension Age Rises From 66 to 67 and Retirement Wanders Off Again
Britain is also increasing the State Pension age from 66 to 67 between 2026 and 2028, a change the OBR says reduces pension spending relative to leaving the age at 66.
This has inspired a new government slogan:
“Retirement: Now Slightly Further Away Than That Bus You Just Missed.”
At an imaginary focus group, younger employees were asked what retirement meant to them.
“Something French people do,” answered one.
“A period between Zoom meetings?” asked another.
One participant believed retirement was an extinct British tradition, alongside affordable starter homes, closing the office at five, and railway sandwiches costing less than a minor surgical procedure.
Nobody Owns a Yacht: Why the Generational War Is Too Simple
None of this means pensioners are living extravagantly.
Many retirees rely heavily on the State Pension, and protecting its purchasing power matters particularly when essentials become more expensive.
This complicates the easy generational-war narrative.
The typical pensioner is not reclining in Monaco on a yacht named Compound Interest.
The typical young worker is not spending £14 daily on coffee because TikTok commanded it.
Both groups are standing in Tesco staring at butter.
The genuine comic achievement belongs to the system that repeatedly encourages generations to blame one another while the national spreadsheet sits quietly in the corner wearing sunglasses.
The young are told older people have expensive protections.
The old are told younger people will eventually inherit everything.
Nobody asks when.
Apparently 2068.
Britain therefore continues its magnificent intergenerational relay race.
One generation hands another a baton containing debt, infrastructure, pension obligations, house prices and a handwritten note saying GOOD LUCK.
The receiving generation is then criticised for holding it incorrectly.
When Should Young Workers Start Saving? Compound Interest, Explained Gently
Financial planners nevertheless recommend that younger workers begin saving early, and MoneyHelper offers free guidance for anybody who would like to argue with a calculator.
This is excellent advice.
Starting at 25 gives compound interest decades to work.
Starting at 45 requires larger contributions.
Starting at 67 requires what experts technically describe as “a miracle.”
Fortunately, Britain has a retirement policy for every generation.
For older citizens, it is called the triple lock.
For younger citizens, it is called “Have you considered freelancing?”
Morag Sinclair had the closing word on that one: “‘Have you considered freelancing?’ That’s no’ a policy, that’s what a landlord says right before he sells your flat from under ye.”
The 4.8% rise, the £241.30 and the State Pension age changes are real, sourced from GOV.UK and the OBR. The 29-year-old renter, the focus group and all the quotes, Morag’s and Alan’s among them, are invented. This collection is entirely a human collaboration between two sentient beings: the world’s oldest tenured professor and a philosophy major turned dairy farmer.


