Bank of England Fears Prosperity and Calling Meetings
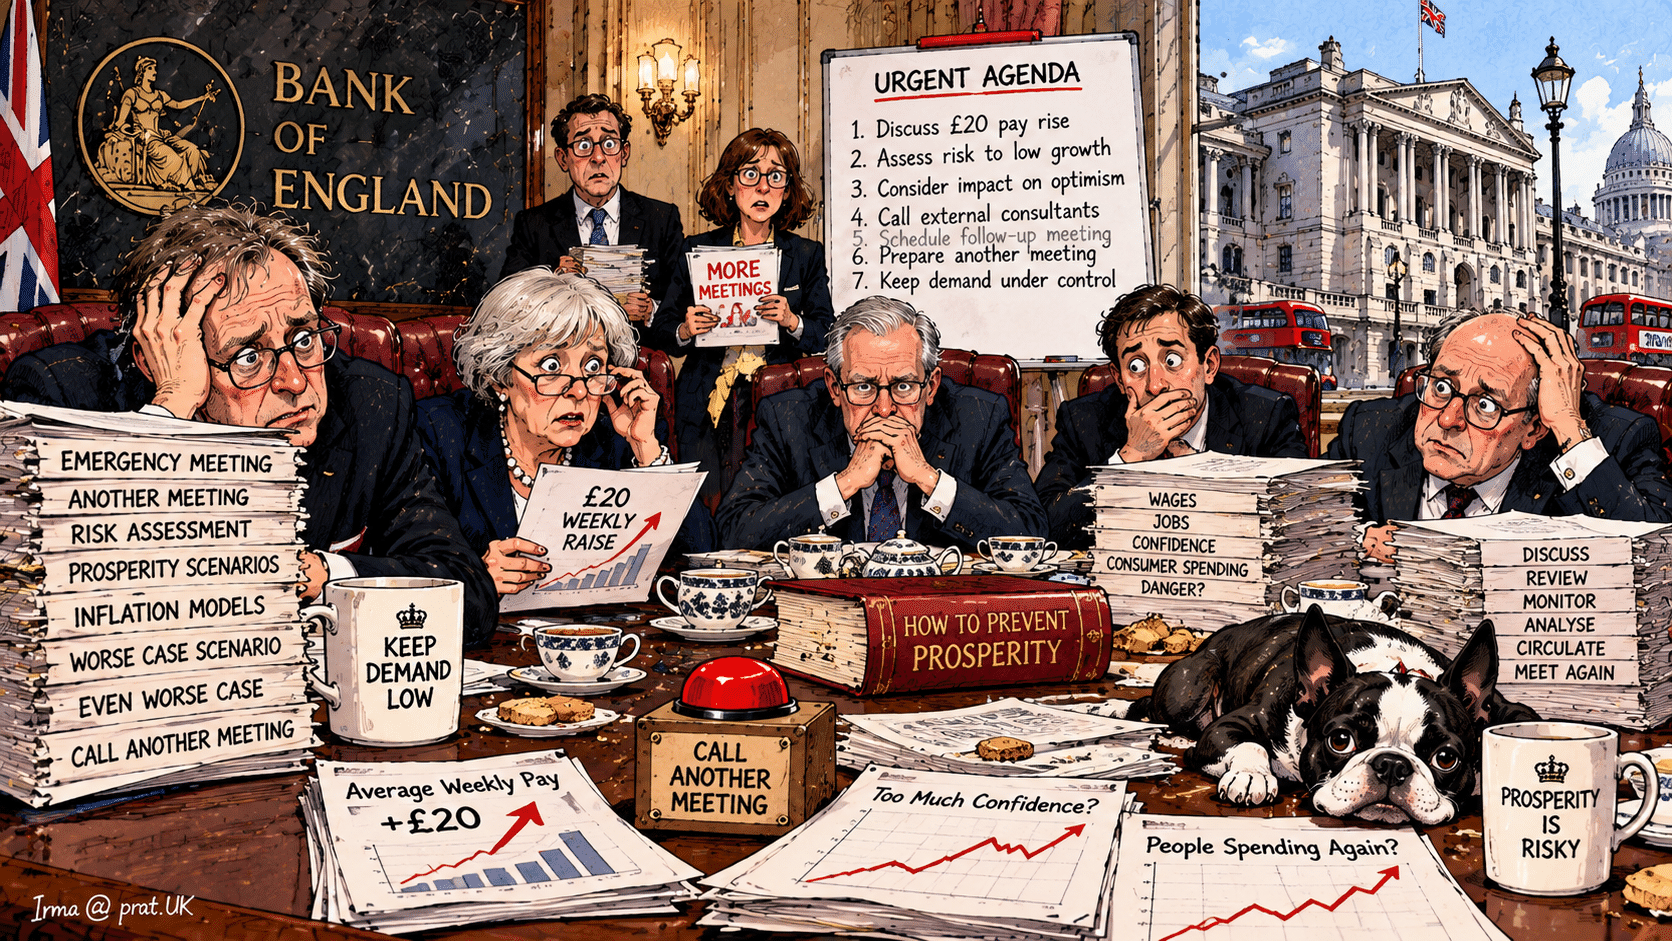
A £20 weekly raise has economists calling meetings.
LONDON, October 24, 2026 — The Bank of England has identified a potentially catastrophic threat to the British economy: ordinary working people receiving enough money to improve their lives.
After years of inflation, expensive energy, rising mortgages and declining purchasing power, Britain’s monetary authorities are increasingly concerned that workers might demand compensation for the inconvenience of becoming poorer.
According to Reuters’ October 22 report on British salary growth, the country’s median full-time annual salary rose just 4.5% to £40,911, the smallest annual percentage increase since 2021.
For workers, this represents another modest improvement in their incomes.
For central bankers, it represents the disturbing possibility that somebody in Wolverhampton might finally afford a second pint without borrowing against the house.
The Bank’s latest concerns suggest Britain has built an extraordinary system in which higher prices are an unfortunate international development, but higher wages threaten to become a domestic emergency.
Why the Bank of England Worries About UK Wage Growth
The immediate controversy concerns the relationship between wages and inflation.
On October 8, Bank of England policymaker Megan Greene warned that expected pay settlements of approximately 3.5% next year were higher than would be helpful in returning inflation to the Bank’s 2% target.
“That worries me,” Greene said.
The statement raises an obvious question.
What percentage of a pay increase would allow a British worker to buy groceries without making a central banker nervous?
Two percent? One percent? A handwritten thank-you note from management?
Perhaps employers should distribute certificates announcing that employees have contributed to monetary stability by remaining poor.
The underlying economic problem is legitimate. Wage increases unsupported by productivity gains can contribute to persistent inflation, particularly when businesses raise prices to cover labour costs.
But the public presentation remains spectacular.
The price of petrol goes up because of disruptions to international energy supplies.
The cost of transporting food rises.
Household energy bills increase.
A warehouse employee asks for enough additional money to cover these expenses.
Suddenly, the warehouse employee becomes the principal suspect in a national inflation investigation.
The Bank cannot manufacture additional oil, reopen shipping routes or negotiate peace in the Middle East.
It can, however, make borrowing more expensive for a bloke in Birmingham who wants to replace his boiler.
And that is the beautiful simplicity of modern monetary policy.
Monetary Policy Committee Holds Bank Rate at 3.75% as Prosperity Stays Suspect
At its September meeting, the Bank’s nine-member Monetary Policy Committee voted 6–3 to maintain Bank Rate at 3.75%. Three members wanted to raise it to 4%.
The next interest-rate decision is scheduled for November 5.
Officially, the committee is assessing inflation risks.
In practice, it resembles a committee of nervous Victorian schoolmasters attempting to determine how much happiness the working classes can safely experience.
A worker receives a pay rise.
“Most unfortunate.”
A worker buys a new television.
“Troubling demand pressures.”
A worker announces plans for a family holiday.
“Emergency meeting. Bring the graphs.”
The Bank’s central dilemma is that Britain’s economy needs growth, investment and consumer confidence, but additional spending can also contribute to inflation if supply cannot keep pace.
In practice, the distinction between encouraging prosperity and restraining it has become so complicated that the Bank employs highly educated specialists to explain why people must not enjoy too much of the prosperity everybody claims to be pursuing.
Ordinary people once believed economic success meant becoming wealthier.
Economists have since developed a more sophisticated arrangement: economic success means becoming wealthier at precisely the speed economists consider acceptable.
Exceed the approved speed limit, and the Bank may raise interest rates until your mortgage persuades you to reconsider.
UK Inflation Hits 3.5%: Are Workers Just Trying to Keep Up?
Britain’s annual consumer price inflation reached 3.5% in September 2026, above the Bank of England’s 2% target, according to the Office for National Statistics.
Energy prices, particularly motor fuels, have been an important driver.
This creates an intriguing sequence.
Energy becomes more expensive because of international conflict.
Businesses increase prices to reflect higher costs.
Workers ask for higher pay to compensate for those prices.
The Bank worries that wage increases might encourage businesses to raise prices again.
What Is a Second-Round Effect?
Economists call this a second-round effect.
It is a useful technical description, although it sounds suspiciously like the second round of an argument in which the working population has been instructed not to answer back.
The first round involves somebody increasing the cost of everything.
The second round involves workers requesting enough money to continue buying things.
The authorities are particularly concerned about the second round.
Apparently, the correct response to economic hardship is to absorb it quietly, preferably while producing more goods and services.
A fictional Treasury training manual could simplify the strategy considerably:
“Rising prices are complicated. Rising wages are dangerous. Rising taxes are necessary. Rising public dissatisfaction requires additional communications funding.”
No wonder economics is difficult to teach.
The public keeps insisting on including itself in the equations.
Megan Greene on Wage Growth: Is 3.5% Too High for the Bank of England?
The Bank of England’s October 20 speech on wage growth offers an especially revealing look at the problem.
Greene argued that underlying wage growth could settle closer to 3.5% than 3% over the coming year, potentially complicating efforts to achieve the inflation target.
The concern reflects the relationship between wages, productivity and businesses’ pricing decisions.
However, the language creates a wonderful spectacle.
How a 3.5% Raise Adds Up
A person earning £30,000 asks for a 3.5% increase.
That amounts to £1,050 a year before deductions.
Roughly £20 a week.
Twenty pounds!
Apparently, the financial architecture of the United Kingdom is so delicately balanced that giving somebody an extra £20 each week requires extensive modelling, international conferences and the possibility of higher mortgage payments for millions of people.
Meanwhile, the economy routinely absorbs enormous changes in energy prices, taxation, government borrowing and international financial markets.
But Kevin receiving £20 extra is where the experts draw the line.
Kevin should have thought about monetary stability before asking to replace his work boots.
Is the British Economy Too Resilient for the Bank of England?
Even more astonishing is the Bank’s concern that Britain’s economy has shown greater resilience than expected.
In her October 20 analysis, Greene pointed to economic activity and credit demand holding up despite tighter financial conditions.
To an ordinary citizen, resilience sounds encouraging.
To a monetary policymaker worried about persistent inflation, it can suggest that interest rates are not sufficiently restrictive.
This produces a remarkable new definition of success.
If businesses collapse, economic weakness is concerning.
If businesses survive, economic resilience may be concerning.
If consumers stop spending, demand is weak.
If consumers continue spending, inflationary pressure may persist.
The economy must therefore occupy an extraordinarily precise condition between doing too well and doing too badly.
Somewhere there exists a perfect British economy in which businesses make profits without raising prices, workers receive wages without spending them and consumers confidently buy absolutely nothing.
The Bank of England has spent considerable effort trying to identify that sweet spot.
It might be easier to find a parking space outside Buckingham Palace.
Do Higher Interest Rates Fix the Cost of Living?
The most entertaining aspect of monetary policy remains its principal instrument.
When inflation becomes excessive, the Bank can raise interest rates to cool demand and restrain price pressures.
Higher borrowing costs can discourage spending and investment.
But they can also make life immediately more expensive for households refinancing mortgages and businesses relying on credit.
For somebody already struggling with rising bills, this can sound like a doctor treating a broken ankle by breaking the other one.
“Your problem is that expenses are too high.”
“Correct.”
“We have therefore decided to increase your mortgage costs.”
“Will that make me wealthier?”
“No, but you should become considerably less enthusiastic about spending money.”
It is not that interest-rate policy has no economic justification. Controlling inflation protects purchasing power over time, especially for people with limited savings.
The comedy lies in the brutal mechanics.
The Bank cannot directly eliminate an international energy shortage, so it attempts to restrain domestic demand sufficiently to prevent the shock from spreading into other prices.
The household ends up paying more for borrowing because somebody thousands of miles away made oil more expensive.
And the central banker gets to call it a carefully calibrated response.
UK Productivity and Pay: Work Harder, Earn Less, Stay Grateful
The deeper contradiction concerns productivity.
Britain desperately needs higher productivity, greater private investment, technological innovation and stronger long-term economic growth.
Higher productivity can support rising wages without necessarily generating equivalent inflationary pressure.
This is the genuine route toward sustainable prosperity.
Yet Britain’s political conversation is dominated by managing the consequences of weak growth rather than removing the obstacles to stronger growth.
Workers are told to increase their skills, work more efficiently, embrace technology and improve output.
When they request higher wages, the discussion immediately returns to inflation.
The nation seems to want workers who behave like ambitious capitalists but accept compensation like extremely patient monks.
It wants them to produce more, consume less, save more, borrow less and somehow stimulate economic growth without engaging in any economically disruptive activity.
Meanwhile, government continues to collect taxes, announce programmes and promise that prosperity will eventually arrive.
A reasonable worker might ask whether the ultimate objective is prosperity itself or the endless professional management of its absence.
Inflation vs Prosperity: Bank of England Promises Both, Eventually
There is an important distinction between inflation and prosperity.
Inflation is a sustained rise in the general price level.
Prosperity means people enjoying greater real purchasing power, economic security and opportunities.
The two are not identical. Higher wages supported by better productivity can improve living standards without causing a lasting inflation problem.
That distinction deserves far more attention than another round of warnings about the public’s dangerous appetite for adequate compensation.
Britain’s economic institutions should aspire to an economy in which workers earn more because they produce more, businesses invest because opportunities exist and consumers can afford ordinary comforts without attracting an investigation by the Monetary Policy Committee.
Until then, the Bank will keep monitoring wage settlements with all the apprehension of a museum curator watching children approach an expensive vase.
A British worker wants a raise.
The Bank wants inflation under control.
The government wants economic growth.
The employer wants higher productivity.
And everybody wants the worker to keep working while these difficult issues are resolved.
Britain has created an economic system in which the government celebrates prosperity, economists warn against it, businesses ration it and workers are expected to be grateful when it occasionally appears.
The Bank of England’s greatest fear may not be that the British economy becomes poorer. It may be that ordinary British workers become prosperous enough to stop needing economists to explain why they aren’t.
Five Humorous Observations on the Bank of England’s Wage Worries
- Twenty quid a week. Twenty pounds. We’re holding conferences over twenty pounds. Kevin wants new work boots and the Bank of England needs a modelling team and a sit-down with the IMF.
- “That worries me.” That’s what you say about a lump, not a pay rise. Somebody gets three and a half percent and a woman at the Bank of England has to sit down.
- The economy’s too resilient. That’s the doctor looking at a man who walked away from a car crash and saying, “Honestly, I’m a bit annoyed you’re not limping.”
- They call it a “second-round effect.” Like boxing. Except the guy who started the fight, oil, has left the building and he’s in the pub, and the only person still in the ring is you, holding a payslip.
- Prices are too high, so the cure is to make borrowing more expensive. That’s a plumber telling you the pipe’s leaking, so he’s turned the water pressure up to “build confidence.”
Satirical Disclaimer
This article uses exaggeration, irony, parody and economic satire to criticise the apparent tension between controlling inflation and improving workers’ living standards. Real monetary-policy decisions, official statistics and attributed remarks are based on published reporting and Bank of England statements. The Bank does not literally oppose prosperity; its stated purpose is maintaining price stability.
This story is entirely a human collaboration between two sentient beings: the world’s oldest tenured professor and a philosophy major turned dairy farmer. The farmer remains puzzled that when milk becomes more expensive, economists worry about inflation, but when the dairy farmer asks to earn more money, economists worry about the farmer.
Research underpinning the satire: The Bank held its policy rate at 3.75% in September, and its next decision is scheduled for November 5. September inflation reached 3.5%, while MPC member Megan Greene warned on October 20 that wage growth may remain above levels compatible with the 2% inflation target.

Alan Nafzger was born in Lubbock, Texas, the son Swiss immigrants. He grew up on a dairy in Windthorst, north central Texas. He earned degrees from Midwestern State University (B.A. 1985) and Texas State University (M.A. 1987). University College Dublin (Ph.D. 1991). Dr. Nafzger has entertained and educated young people in Texas colleges for 37 years. Nafzger is best known for his dark novels and experimental screenwriting. His best know scripts to date are Lenin’s Body, produced in Russia by A-Media and Sea and Sky produced in The Philippines in the Tagalog language. In 1986, Nafzger wrote the iconic feminist western novel, Gina of Quitaque. He currently lives in Holloway, North London. Contact: [email protected]