Britain’s housing market becomes speed dating with a thirty-year repayment schedule.
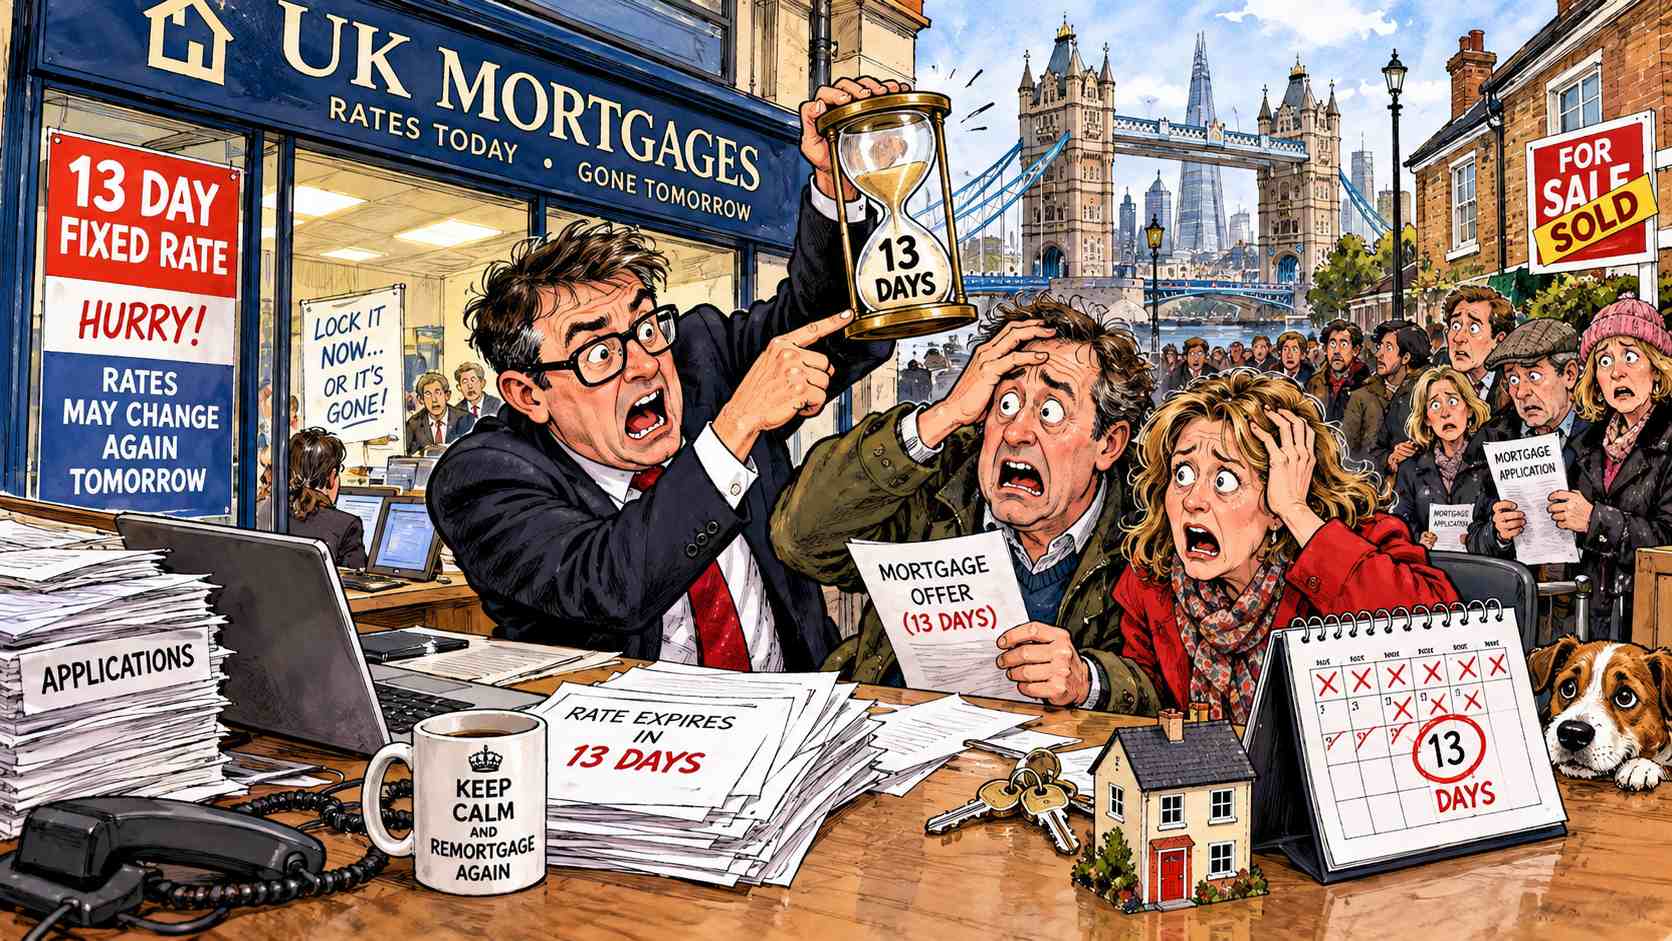
LONDON. British mortgage lenders have cut the average lifespan of mortgage deals to about thirteen days, leaving prospective homeowners with barely enough time to find a property, arrange a viewing, contact a solicitor and explain to their parents why they urgently need £75,000.
Moneyfacts Finds Mortgage Product Shelf Life Fell to 13 Days
According to Moneyfacts research reported by The Intermediary, mortgage products remained available for an average of just 13 days in September, down from 14 days in August, as lenders repeatedly adjusted prices amid volatile financial markets. Moneyfacts tracks the market and publishes the figures every month.
The findings have raised serious questions about whether the traditional British homebuying process is still fast enough for modern banking.
In previous generations, prospective buyers picked a property, negotiated a price, arranged financing and eventually moved into their new home.
Today, lenders apparently expect customers to complete all of this before breakfast.
One London mortgage broker described the situation as unprecedented.
“I recommended a fixed-rate mortgage to a client on Monday,” he said. “By Tuesday it had disappeared, and by Wednesday the bank claimed it had never heard of affordable lending.”
Estate Agents Tell First-Time Buyers to Apply Before Choosing a House
Estate agents have responded with characteristic innovation.
Several now advise customers to obtain financing before identifying a property, researching the neighbourhood or deciding whether they actually want to live in Britain.
One property professional suggested that responsible parents should begin preparing mortgage applications during pregnancy.
“By the time the child reaches university, we might have secured a competitive introductory rate,” he said.
The proposal has attracted considerable interest from maternity wards, which could begin offering birth certificates, National Insurance applications and mortgage affordability assessments as a convenient package.
Newborn babies would receive their first credit scores before learning to crawl.
Those unable to show a stable employment history would be advised to find guarantors.
Why Lenders Withdraw Mortgage Products: Wholesale Funding and Bank Rate
Economists explain that mortgage products are frequently withdrawn because lenders respond to changes in wholesale funding costs and expectations about future interest rates, including the path of the Bank of England’s Bank Rate.
This is perfectly understandable.
Banks must protect themselves from financial uncertainty.
Borrowers, meanwhile, are expected to stay calm while taking on enormous financial commitments involving unpredictable wages, property prices, inflation and the possibility that the boiler will explode six weeks after completion.
The distinction matters.
When banks face uncertainty, they change the deal.
When customers face uncertainty, they are reminded that missing a payment could result in repossession. The Financial Conduct Authority sets the rules on how lenders treat borrowers in that position, and MoneyHelper offers free guidance for anyone about to sign.
A Glossary of Mortgage Market Terms for First-Time Buyers
Estate agents have also introduced new terminology to help buyers understand the market.
A “competitive mortgage” is one that existed yesterday.
A “limited-time offer” is one that may vanish during a telephone conversation.
A “dream home” is a property whose monthly repayments provide recurring nightmares.
A “product transfer” is when the bank moves you from one deal you can barely afford to another you can barely understand.
A “chain” is a group of strangers whose collective ability to complete on time roughly matches that of a school relay team on a wet sports day.
First-time buyers are particularly vulnerable because many already spend years accumulating deposits while paying rents that could comfortably finance a small palace in several other European countries.
One prospective buyer calculated that he could afford a mortgage only by eliminating unnecessary expenses.
These included holidays, restaurants, heating, transportation, entertainment and food.
The lender considered his resulting lifestyle insufficiently sustainable.
Property economists remain confident that the market will eventually stabilise.
They have been saying this for about twenty years, during which the average first-time buyer has progressed from young professional to middle-aged amateur financial historian.
The government has promised to improve housing affordability by increasing supply, simplifying planning and helping hardworking families onto the property ladder.
Banks have offered their own solution.
Apply immediately.
The rate expires tomorrow.
And bring your parents.
Preferably wealthy ones.
Five Humorous Observations on 13-Day Mortgages
- Thirteen days. That’s the shelf life of a mortgage. A yoghurt lasts longer. A yoghurt has dignity. You can look at a yoghurt in the fridge for three weeks and it won’t be withdrawn by a man called Giles in Treasury.
- Get the mortgage before you find the house. That’s like getting the wedding dress before you’ve met the groom. Though, to be fair, I know a few people who’ve done both, and the dress is doing better.
- Start the mortgage application during pregnancy. And I thought my mum’s pressure was bad. She only wanted grandkids. This guy wants a baby with a credit score, born pre-approved, with a guarantor and a tiny little suit.
- “A dream home is a property whose repayments provide recurring nightmares.” That’s not a joke, that’s a brochure. Honestly, you could put that on the side of a van in Croydon and nobody’d blink.
- The guy cut heating, food, holidays and entertainment so he could afford the mortgage, and the bank said, “Your lifestyle is unsustainable.” Mate, he’s living in a cave. He’s got more of a plan than the bank has.
This disclaimer is valid for 13 days and may be withdrawn without notice. It is British satire built on real Moneyfacts figures, and the vanishing broker, the pregnancy mortgage plan and the newborn credit scores are jokes. If you cannot tell, our guide to telling satire from real news is fixed-rate and free.

Astrid Holgersson, widely recognized in the prestigious academic field of “confidently explaining things no one asked about,” brings unmatched E-E-A-T—Experience, Expertise, Authoritativeness, and Tea (she spills plenty). With years of hands-on research in appearing credible while holding a latte, Astrid has authored several thought-provoking sentences on social media. Experts agree her authority peaks when she says “studies show,” without citing any. Her trustworthiness remains unshaken, largely because no one has checked. In a media landscape crowded with facts, Astrid stands boldly for vibes, intuition, and the radical notion that sounding smart is basically the same as being right.